The laser industry is entering a transformative decade. By 2035, the global market for laser systems, components, and materials is projected to reach approximately $33.8 billion, driven by accelerating adoption across manufacturing, healthcare, telecommunications, and defense . Within this broader ecosystem, two interconnected segments are creating substantial B2B opportunities: the laser components market and the laser spare parts market.
For laser manufacturers, equipment OEMs, and component distributors, understanding the 2026–2035 outlook is essential for strategic positioning. This analysis examines the size, growth drivers, and competitive dynamics shaping these markets.
Market Sizing: What Are We Looking At?
✅ Laser Components Market
The global laser optics market—a core subset of the broader components category—was valued at $9.8 billion in 2024** and is projected to reach **$33.76 billion by 2035, representing a compound annual growth rate (CAGR) of 11.9% . This accelerated pace reflects the growing sophistication and value of optical subsystems in modern laser applications.
More broadly, the global market for laser systems, components, and materials is expected to grow from $21 billion in 2024 to $30.4 billion by 2029, at a CAGR of 7.7% . The faster growth of the pure components segment highlights a structural shift: as laser systems proliferate, the demand for replacement parts, upgrades, and consumables is outpacing new equipment sales.
✅ Laser Spare Parts Market
While precise global figures for the spare parts segment are challenging to isolate, the aftermarket—including consumables and replacement parts—already accounts for 25–35% of total annual revenue in categories like laser cutting heads, and this share is rising . In China alone, the aftermarket represents approximately 45–50% of the laser machine components market by value, driven by the large installed base of laser equipment entering peak replacement cycles.
Key Growth Drivers (2026–2035)
✅ 1. Accelerating Industrial Automation and Precision Manufacturing
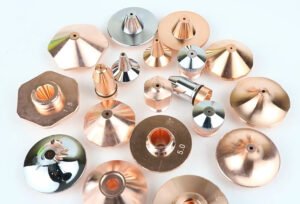
Factories worldwide are replacing traditional cutting and welding methods with laser-based solutions, particularly in automotive, electric vehicle (EV) battery manufacturing, and sheet metal fabrication . This drives demand for both first-fit components and spare parts like nozzles, protective windows, and focus lenses.
✅ 2. The Rise of High-Power and Ultrafast Laser
The transition to fiber laser architectures—now dominating metal cutting—increases demand for pump diodes, delivery fibers, and beam-combining optics . Meanwhile, ultrafast lasers are gaining traction in electronics micromachining and medical device production, creating a premium component segment with higher per-unit value and stricter quality specifications.
✅ 3. Expansion of Semiconductor and Electronics Manufacturing
Semiconductor wafer fabrication and advanced packaging are growing at 12–15% annually, creating new demand for precision laser components used in lithography, inspection, and trimming applications . By 2035, the semiconductor and precision manufacturing segment could approach 20–25% of total laser component demand.
✅ 4. Aftermarket Demand from a Growing Installed Base
The global installed base of laser cutting machines is estimated at well over 600,000 units, with replacement cycles of 5–8 years for core subsystems and 3–5 years for consumables . Machines installed during the 2018–2024 expansion wave are now entering their peak renewal phase—a recurring revenue opportunity for suppliers and distributors.
Regional Dynamics: Who Leads and Who's Growing Fastest?
| Region | Market Share / Growth | Key Characteristics |
|---|---|---|
| Asia-Pacific | Largest market; China accounts for 35–45% of global demand | Dominates both consumption and production of mid-range components |
| China | Growing at 9–11% CAGR (2026–2035) | Domestic production covers 70–75% of standard modules, but high-end optics remain 20–25% imported from Germany and Japan |
| India & Southeast Asia | Fastest-growing secondary markets (9–12%) | Expanding laser machine assembly operations; heavily reliant on imported components |
| Europe (Germany) | Technology leader for premium heads and optics | High-power, precision-grade segments command 30–40% price premiums |
| North America | Moderate growth (4–6%); strong aftermarket | Reshoring in electronics and semiconductors may increase domestic demand for micro-machining heads |
Price Trends: Premium vs. Commoditization
A bifurcation in pricing is emerging:
- Standard-grade components (protective windows, basic nozzles, low-power lenses): Prices are declining at 3–5% per year due to intense competition from Chinese and Southeast Asian suppliers.
- Precision-grade components (zero-defect optics, high-laser-damage-threshold coatings, 10kW+ heads): Command a 30–40% premium and see less price erosion due to limited supplier qualification and high barriers to entry.
This dynamic creates a clear strategic choice: compete on volume in commoditized segments, or specialize in high-performance, high-margin components where certification and precision are the differentiators.
Strategic Implications for B2B Buyers
✅ For Laser Manufacturers and OEMs
- Dual-sourcing for critical components is becoming essential to mitigate geopolitical and supply chain risks.
- Supplier qualification takes 12–24 months—start the validation process early to secure reliable partners.
✅ For Component Distributors
- Aftermarket revenue is rising—position your business around replacement parts, consumables, and maintenance kits.
- Price-sensitive buyers are a growing segment; consider offering tiered product lines (standard vs. premium).
- Technical support is a competitive advantage: B2B buyers increasingly seek partners who understand system integration, not just parts replacement.
✅ For Equipment OEMs
- Total cost of ownership matters more than initial price—emphasize lens life, local service, and system reliability to command premium pricing.
- Invest in modular head architectures that allow field-upgrade of lenses and sensors, creating recurring revenue opportunities.
Conclusion: Positioning for 2035
The laser components and spare parts markets are entering a decade of robust growth, with the aftermarket becoming an increasingly critical revenue stream. For B2B players, success will depend on:
- Strategic sourcing: Build relationships with qualified suppliers early.
- Price-tier strategies: Offer both standard and premium product lines to capture diverse customer segments.
- Aftermarket focus: Leverage the growing installed base for recurring spare parts revenue.
- Regional agility: Adapt to localization pressures and supply chain realignment.
As the global installed base of laser equipment expands and technology continues to evolve, companies that understand these dynamics—and act on them—will be best positioned to thrive through 2035 and beyond.